Record tech profits obscure the structural fragility of Korea’s single-engine economy
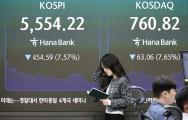
Economic success can conceal the cost of economic dependence. South Korea offers a case in point: A semiconductor boom has raised growth forecasts and delivered record corporate earnings, yet its stock market has been gripped by panic, with repeated trading halts.
The disconnect, even as Samsung Electronics reported unprecedented quarterly operating profits last week, points to a structural weakness in an economy whose fortunes rest too heavily on a single industry.
The sell-off reflects several converging pressures: Renewed US inflation concerns have unsettled interest-rate expectations, doubts have emerged over the financing of artificial intelligence infrastructure, and Chinese memory chip-makers are challenging assumptions about Korea’s technological lead.
Taken together, these developments illustrate the vulnerability of a growth model tethered to global demand for memory chips.
Hotter US inflation data has revived fears that borrowing costs will remain elevated, weighing on technology shares worldwide. Rising bond yields for AI infrastructure provider CoreWeave have added to the unease. Its financing arrangements and close commercial ties with Nvidia have drawn scrutiny to the circular relationships underpinning parts of the AI investment boom.
If expensive credit forces major technology companies to curb infrastructure spending, memory demand could weaken sooner than Korean producers anticipate. Record profits offer little shelter when the market begins to question what comes next.
China poses a longer-term challenge. ChangXin Memory Technologies, or CXMT, has announced plans to introduce server DRAM using a new architecture, which reduces memory-cell area by roughly one-third compared with the conventional design.
Yet its commercial production at competitive yields remains uncertain, and the announcement does not prove that Chinese manufacturers have overtaken their Korean rivals.
However, treating the claim as mere publicity would be complacent. China has repeatedly deployed state-backed investment and alternative technological approaches to challenge established industrial leaders.
Its strategy can involve changing the terms of competition rather than simply copying the incumbent’s methods. Memory chips may prove harder to disrupt than telecommunications equipment or electric vehicles, but Korea cannot assume its lead will endure.
The market reaction also reflects a domestic weakness. Semiconductor earnings dominate expectations for corporate profits, exports and growth. When confidence in the sector falters, the shock spreads across the economy.
Other manufacturing pillars offer limited reassurance. Petrochemicals and steel face pressure from Chinese overcapacity and trade barriers, while electric vehicle makers confront aggressive foreign competition and shifting industrial policies.
The Korea Development Institute has warned that Korea could enter a period of negative growth around 2030 if its long-term decline in growth potential continues.
That warning deserves more attention than another upward revision to the annual growth forecast. Export windfalls can inflate headline figures without reversing weak productivity or creating durable sources of demand.
Building expansive spending plans around semiconductor-related tax revenue would compound the danger if the boom fades. Fiscal policy should preserve room to respond to future shocks rather than treat an exceptional revenue cycle as a permanent funding source.
Structural reform cannot wait for the next downturn. The Korean government should remove unnecessary barriers to corporate investment, make labor markets more adaptable, and open a greater scope for new businesses to challenge established players. It should also help capital and talent move into promising industries beyond semiconductors while maintaining fiscal discipline.
A stock market rout cannot diversify an economy. It can expose the price of failing to do so. Korea’s semiconductor boom has bought time, but that reprieve will matter only if policymakers and businesses use it to build a broader base of productive activity. When the chip cycle turns, the strength of that foundation will count for more than the profits that preceded it.
khnews@heraldcorp.com