Record earnings and emerging growth drivers signal a positive shift for major K-pop stocks
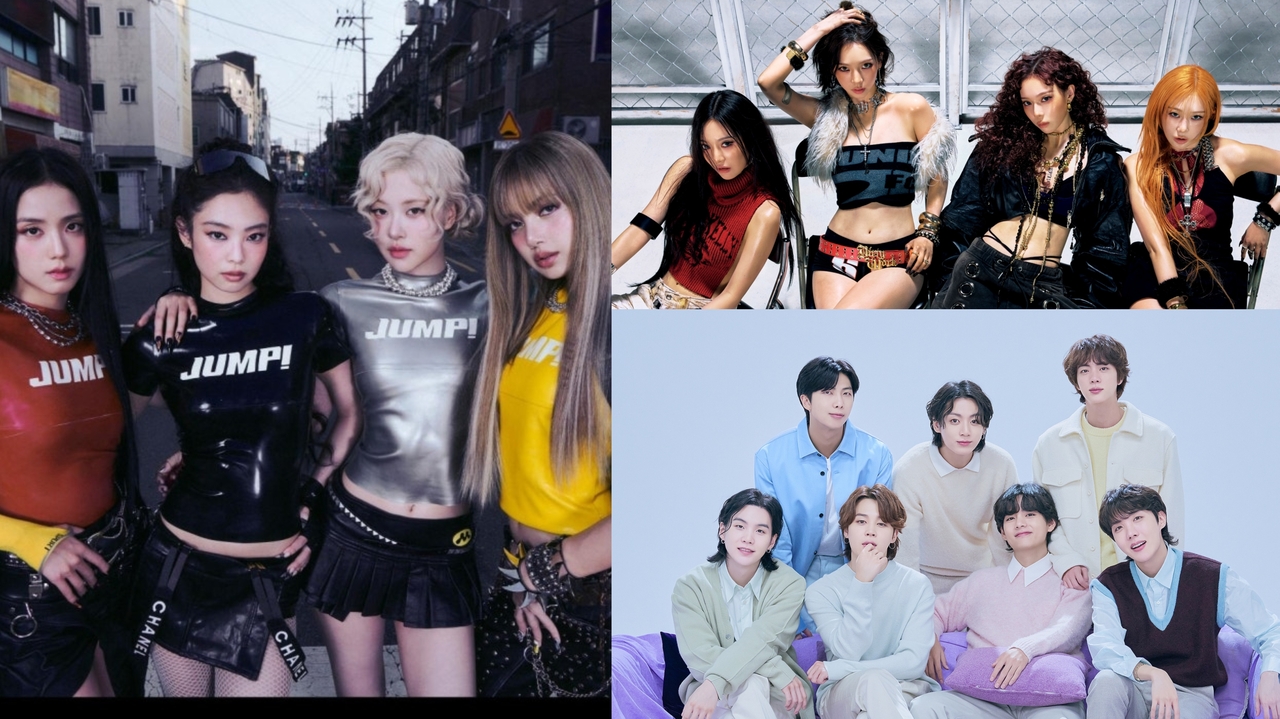
Quiet but resilient, K-pop labels weather the turbulence of the stock market, buoyed by improving earnings and emerging growth drivers.
July was a tough month for K-pop stocks as they lagged behind the broader market, with investors questioning growth prospects. South Korea’s top four K-pop giants — Hybe, SM, YG and JYP — saw an average decline of 9 percent, in contrast to the Kospi’s 4 percent and Kosdaq’s 2.5 percent gains. The disappointment was compounded by unmet expectations that the sector, shielded from tariff risks, would outperform others.
However, the tide has shifted, with signs of recovery emerging across the K-pop sector.
Solid earnings were a common theme, with Hybe, SM and YG surpassing or meeting market expectations in the second quarter.
Hybe posted record revenue of 705.6 billion won ($507 million), a 10 percent increase on-year, with operating profits rising 29 percent to 65.9 billion won, driven by balanced growth in concert revenues and merchandise sales.
SM exceeded expectations, with revenue climbing 19.3 percent to 302.9 billion won and operating profit soaring 92.4 percent to 47.6 billion won, fueled by record merchandise sales. YG returned to profitability, reporting an operating profit of 8.4 billion won, supported by Blackpink’s world tour.
Though not officially released, industry expectations for JYP's second-quarter earnings are strong, supported by strong album and concert sales, with IBK Securities predicting a nearly 100 percent increase in revenue and a 60 percent rise in operating profit.
By the first week of August, the four stocks had recouped July’s losses, surging 9.5 percent, driven by strong second-quarter earnings and signs of an industry-wide recovery.
Hybe led the rally, closing Friday at 291,000 won per share, a 12 percent rise in August. This followed a rebound from July’s losses, which were tied to legal risks surrounding founder Bang Si-hyuk. The stock had dropped 24 percent from June's peak to 246,000 won on July 30 after news of a tax investigation and police raid.
Market watchers largely downplayed a lasting impact from Bang’s legal troubles on the stock price and emphasized the company’s strong revenue growth.
“While Bang’s legal issues may affect the share price in the short term, the company’s expanding artist roster and accelerating earnings momentum should drive growth from 2026 onward,” said analyst Choi Min-ha of Samsung Securities. Choi pointed to the growing artist pipeline, including the debut of a new boy band under Hybe Latin, along with BTS’ highly anticipated world tour next year after a five-year hiatus.
SM’s earnings surprise is particularly significant, pointing to broader industry growth. “The key investment drivers in K-pop now are large-scale world tours by high-profile IPs and a sharp rise in merchandise sales,” said Lee Ki-hoon of Hana Securities. “Three consecutive quarters of surprise results from SM, historically weak in North America, highlight its transformation and the growing potential for K-pop’s monetization.”
The anticipated lifting of the cultural ban on Korean content is another factor expected to boost stock values. Analysts see Xi Jinping’s visit to the APEC summit in Gyeongju this October as the catalyst for the ban’s removal, reopening the Chinese market to K-pop.
SM, strengthening its ties in China, is poised to be the key beneficiary of the reopening.
“SM secured Tencent Music Entertainment as a major stakeholder in May, which is expected to enhance synergies in areas like IP production, concerts, merchandise and visual content,” said analyst Kim Yu-hyuk of IBK Investment. “The TME collaboration should provide significant momentum for stock growth.”
Meanwhile, SM, YG and JYP each closed Friday at 140,200 won, 93,200 won and 79,800 won per share, respectively.
jwc@heraldcorp.com