Retail-driven surge, sharp market swings raise risks, though valuations remain below long-term averages
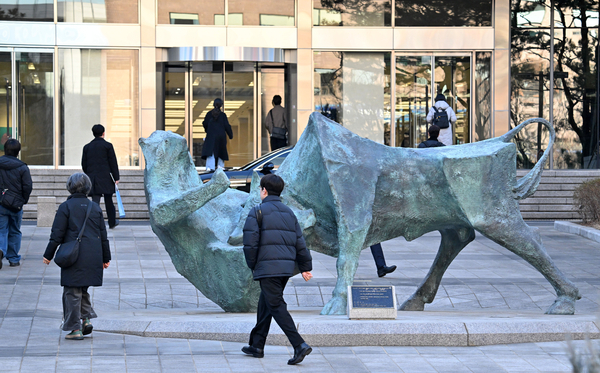
South Korea’s stock market is showing signs of overheating after a yearlong rally, with concerns rising over elevated volatility and stretched valuations.
The benchmark Kospi closed at 5,781.2 on Friday, up 152 percent from its 52-week low of 2,293.7 on April 9, 2025, and 119 percent higher than 2,637.1 a year earlier.
Before the US-Israel joint strikes on Iran, the local stock market had been on a strong upward trajectory. On Feb. 27, a day before the attacks, the index climbed as high as 6,347.41 during intraday trading, hitting a record high.
Volatility, however, has sharply increased as geopolitical risks stemming from war in the Middle East have been priced in. Given the economy’s heavy reliance on energy imports, the impact has been more significant than in other markets.
The Kospi plunged 7.24 percent on March 3, followed by a further 12.06 percent drop the next day — the steepest daily decline on record. It then rebounded 9.63 percent on March 5, highlighting the extreme swings in the market.
During this period, circuit breakers were triggered twice within three trading days, suspending trading for 20 minutes. More sidecar activations followed, curbing program trading for five minutes.
Following the sharp disruptions, the index has struggled to regain momentum, remaining unable to reclaim the 6,000-point level.
The VKospi, the Kospi 200 volatility index, also surged to a record high of 81.99 earlier this month and has since remained above 50, a level widely regarded as signaling market panic. The index is a key gauge of market volatility.
Some global institutions are raising the possibility of a market bubble. Bank of America, in a recent report, described the Korean stock market's movements as the "textbook examples of a bubble."
The report noted the Kospi has been exhibiting extreme volatility, similar to that seen during the 1997 Asian financial crisis, the 1999 dot-com bubble, and the 2008 global financial crisis.
The banking institution added that Korean retail investors have helped fuel a “classic bubble environment” by driving the recent historic rally.
As the BofA pointed out, individual investors have been the main buyers this year, net purchasing 22.16 trillion won ($14.8 billion) worth of Kospi shares, while foreign investors offloaded a hefty 37.53 trillion won. Institutional investors, meanwhile, were modest net buyers, picking up 9.69 trillion won.
Others argue that such concerns are overstated, saying the Kospi still has room for further upside.
“Despite continued policy efforts to ease the Korea discount, the local equity market still remains undervalued in terms of price-to-earnings ratios,” Na Jeong-hwan, an analyst at NH Investment & Securities, said.
“With upward revisions to Kospi earnings forecasts, the 12-month forward PER is at 9.5 times, below the 10-year average of 10.5 times,” he said.
Some also say the ongoing semiconductor supercycle could support a continued upward trend in the Kospi.
"Excluding Samsung Electronics and SK Hynix, Korea’s semiconductor and hardware sector accounts for about 5 percent of the combined Kospi and Kosdaq market capitalization, still below its previous peak of 6.5 percent. This indicates there may be further room for share prices to rise," Hana Securities analyst Lee Jae-man said.
silverstar@heraldcorp.com